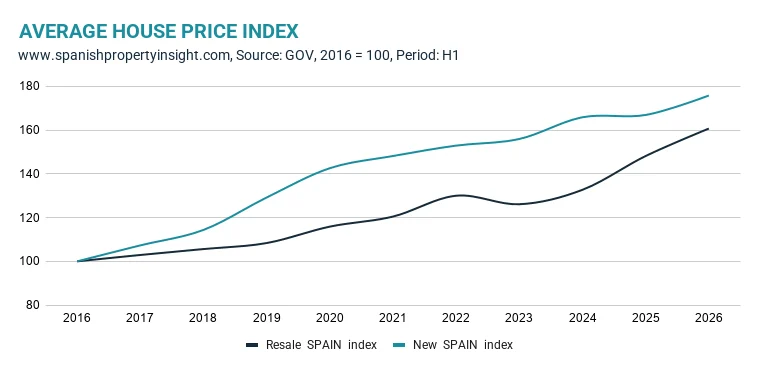
Spanish residential property values continued an upward trajectory during the first half of 2026, registering an annual price increase of 9 per cent. However, data published by Spanish Property Insight reveals that the total aggregate value of transactions stalled during the same period, pointing to a widening disconnect between rising valuations and buyer purchasing power.
Valuation Growth Versus Turnover
The Spanish residential property sector presented a complex picture in the opening six months of 2026. Figures released by Spanish Property Insight indicate that average house prices across the country climbed by 9 per cent compared to the previous year. Yet, despite this persistent upward pressure on per-square-metre metrics, the overall monetary volume of transactions failed to follow suit.
Over the past decade, the total size of the Spanish property market has expanded significantly, more than doubling in cumulative transaction volume. Nevertheless, the H1 2026 data shows that total sales value remained largely flat. This divergence suggests that while individual assets are commanding higher prices, the sheer quantum of capital changing hands has reached a temporary plateau.
Affordability Ceilings and Buyer Resistance
The stagnation in total sales value strongly indicates that domestic and international buyers are encountering strict financial boundaries. As asking and closing prices outpace broader wage growth and household income increases, purchasing capacity is constrained. Mortgages have grown more expensive over recent cycles, altering debt-servicing calculations for retail buyers.
Market analysts suggest that sellers may be testing the upper limits of what the current buyer pool can support. While prime urban locations and established coastal enclaves continue to attract liquidity, secondary markets and properties requiring substantial renovation are experiencing longer days on market as prospective purchasers exercise greater caution.
Supply Dynamics and Regional Divergence
New construction output across Spain remains measured, failing to match the robust demand observed in major employment hubs such as Madrid, Barcelona, and high-end coastal corridors like the Costa del Sol and the Balearic Islands. This structural supply shortage acts as a floor beneath prices, preventing meaningful corrections even as transaction velocity cools.
Conversely, inland regions and secondary provincial capitals display more subdued price growth, where local purchasing power dictates market ceilings. Investors operating in these jurisdictions must evaluate yield stability against a backdrop of flatter capital appreciation compared to the prime coastal segments.
- Average Spanish residential property prices increased by 9 per cent in H1 2026 according to Spanish Property Insight.
- Total aggregate transaction value stalled during the same period, indicating potential buyer resistance and affordability ceilings.
- New construction supply remains constrained in prime urban and coastal destinations, supporting current valuation levels.
- Financing costs and stricter debt-servicing criteria continue to influence retail buyer purchasing power across Spain.
- Investors should carefully examine regional divergence, as secondary markets exhibit markedly different liquidity patterns than prime hubs.
The H1 2026 data from Spanish Property Insight illustrates a mature market entering a phase of consolidation. For institutional and private investors, the 9 per cent year-on-year price growth contrasts sharply with flat overall transaction values, signaling that capital preservation and asset selectivity are paramount. While prime assets in Tier-1 cities and established lifestyle destinations retain fundamental demand driven by structural supply deficits, secondary locations warrant cautious underwriting. Yield compression may occur if entry prices continue to climb ahead of local rental market realities. Investors should consult independent legal and financial advisors to assess regional tax obligations, municipal regulations on tourist lets, and exact comparable transaction data before committing capital in this environment.
関連文献
Why Record High Diesel Prices Won’t Stall Economic Growth (Fisher Investments, 22 Sep 2026)
KRUK H1 2026 slides: cash EBITDA rises 8% as profit stalls (Investing.com, 27 Aug 2026)
Bitcoin Price Stalls Below $80,000 as Accumulation Hits Limbo (The Coin Republic, 27 Aug 2026)
Electric cars grab a third of Europe's car sales as Spain picks up speed (RUSSPAIN.com, 7 Oct 2026)
出典とクレジット
- Feature: Spanish house prices rise 9pc but market growth stalls in H1 2026 — Spanish Property Insight. Linked, not reproduced.
- Main image: Spanish Property Insight, from the original feature linked above; all rights remain with the publisher and photographer.
- 見出しはGoogleニュースRSS経由で提供;コンテンツはリンクされた出版社に帰属します。
動画は元のYouTubeチャンネルから埋め込まれており、出版社の所有物です。 ClubProperty 第三者の映像や写真は一切掲載していません。価格や詳細は執筆時点で上記の情報源による報告の通りです。ここに記載されているのは金融アドバイスではありません。
関連記事
高級不動産における建築リノベーションの台頭
AN Interior's latest issue highlights a definitive shift toward adaptive reuse and high-end renovation,…
続きを読むスペイン不動産を所有する英国居住者向けの英国税負担
British expatriates owning property in Spain face complex cross-border tax liabilities concerning rental income,…
続きを読むシュトゥットガルトとポルシェのミッションSの経済的な波紋
シュトゥットガルトの自動車遺産と今後登場するポルシェ・ミッションSが地域不動産にどのような影響を与えているかを検証しましょう...
続きを読むスイスの規制変更とチューリッヒの不動産への影響
UBSの本社移転の可能性は、スイスにおける規制圧力を浮き彫りにし、チューリッヒの...
続きを読む